Why a professional valuation is key to getting your mortgage approved in Qatar
In short: A professional property valuation in Qatar tells the bank the market value of the property, so it can check there is adequate equity before it lends. The Qatar Central Bank sets the maximum loan to value (LTV): up to 80% for Qatari citizens and up to 75% for resident expatriates buying residential property up to QAR 6 million.
Whether you are buying your first home or financing a commercial development, one step can ensure the success of your application: the property valuation.
Before a Qatari bank lends against a property, it needs to ensure that there is adequate equity (the difference between the property value and the mortgage amount) in the property.
A professional valuation assesses the market value of the property, to ensure the buyer is not overpaying and there will be adequate security for the bank.
Why banks in Qatar insist on a property valuation for a mortgage
The Qatar Central Bank sets loan to value (LTV) criteria for property depending on a number of factors shown in the table below.
A property loan is secured against the property itself and the banks rely on an independent opinion of market value from a qualified valuer.
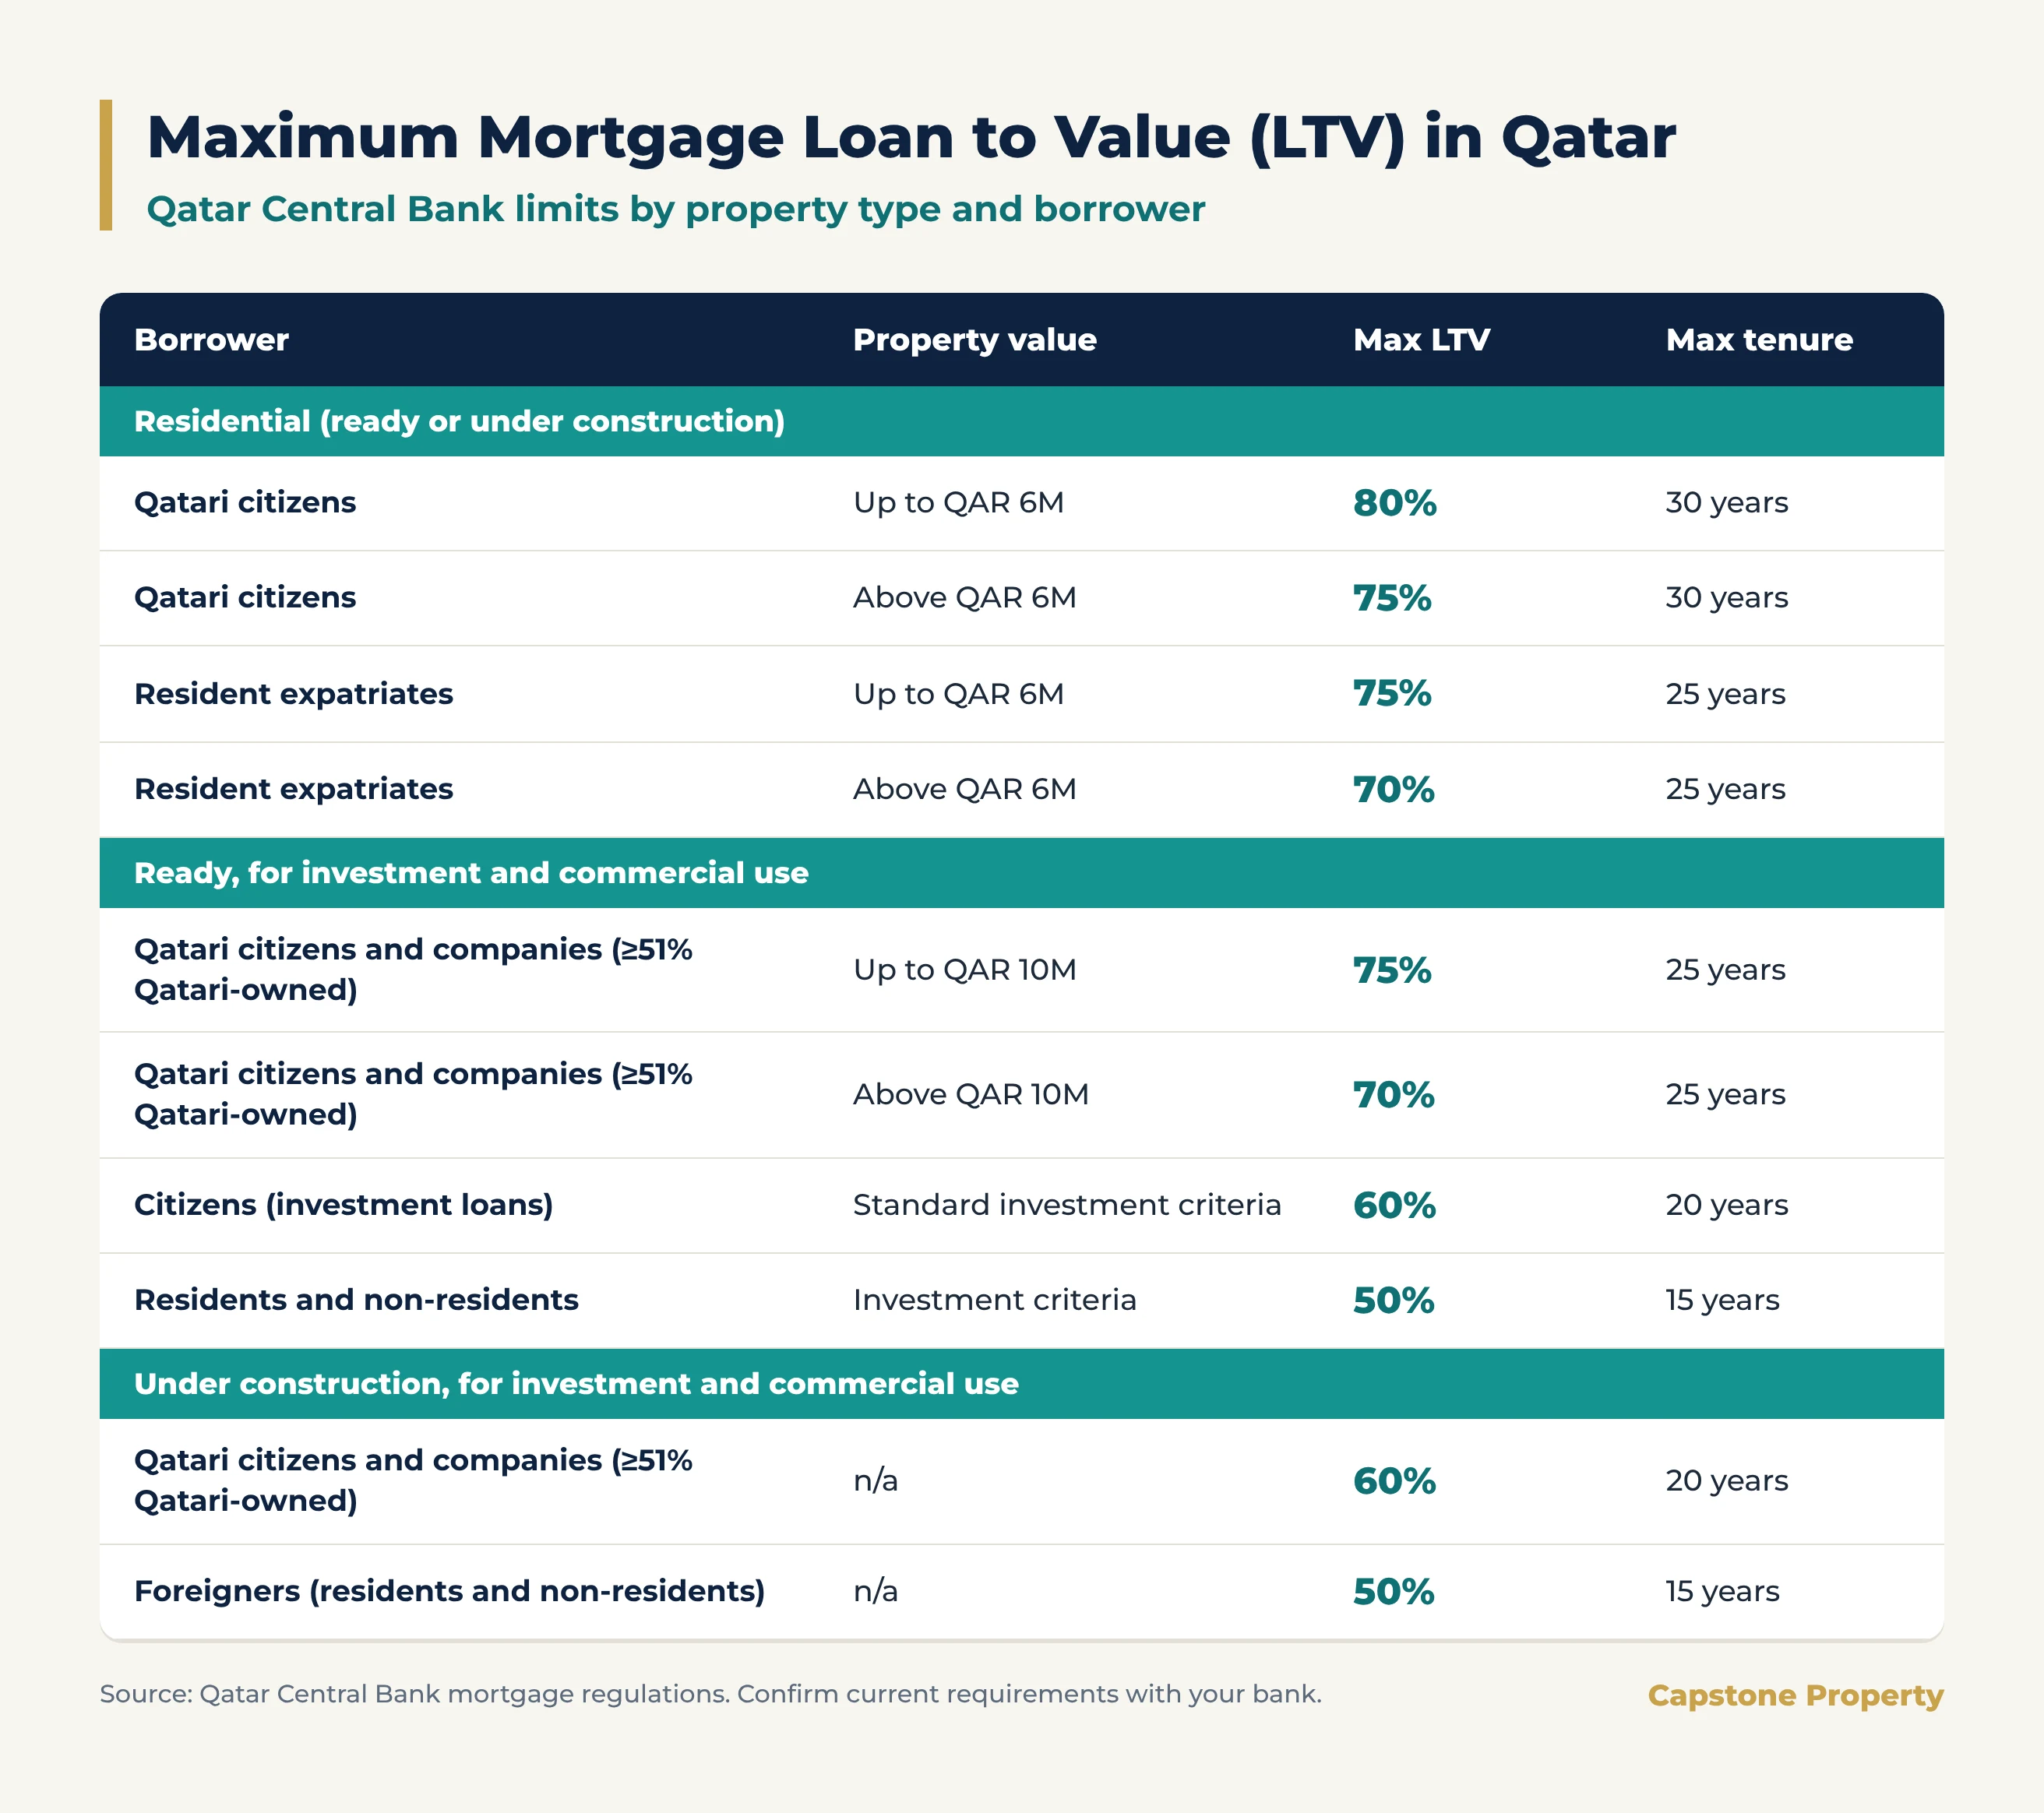
Source: Qatar Central Bank mortgage regulations, as reported by Qatar News Agency.
Property valuation criteria in Qatar: what the valuer checks
A professional valuer carries out detailed inspection to the property using their experience to consider the following factors
Location and surroundings.
Proximity to services, transport and amenities, the quality and positioning of the neighbourhood and its future development plans.
Physical condition.
Age, construction quality, finishes, maintenance and any visible defects.
Size and use.
Built-up area, plot size, layout and the permitted use of the land or building.
Legal standing.
Title deed, ownership documents and any restrictions.
Comparable transactions.
Recent sales and rental evidence for similar properties nearby, which allows the assessment of market value and market rent.
Income potential.
For investment and commercial assets, rental income, occupancy and the strength of the tenant base.
From property valuation to mortgage approval in Qatar
Once a property valuation report is completed, it becomes an essential part of the bank’s mortgage assessment and lending decision. Beyond establishing the property’s market value, the report helps lenders determine an appropriate loan amount, evaluate potential risks, and structure financing terms.
The valuation supports the bank’s overall risk assessment, alongside the borrower’s income, existing financial obligations, and credit history. Properties with strong market demand, reliable valuation evidence, and good resale potential generally present a lower risk than specialised properties with limited marketability.
Real estate valuation approaches banks use in Qatar
Residential valuations generally rely on the comparison approach, examining recent transactions involving similar properties. Factors such as location, property size, condition, quality, and prevailing market conditions are considered when determining market value.
Commercial valuations often require a more detailed financial and market assessment. Depending on the property, valuers may examine rental income, occupancy levels, lease agreements, operating expenses, investment yields, and market demand.
For development properties, additional considerations may include construction costs, planning approvals, development timelines, and the anticipated value upon completion.
Banks financing development projects may also require valuations at different stages of construction to monitor progress, assess the adequacy of their security, and support decisions on further loan disbursements.
Many Qatari banks also consider cost approach valuations where the construction cost of the property is assessed as new and then depreciated to reflect the age, and added to the land value.
Whether residential, commercial, or development-related, an accurate and independent property valuation plays a critical role in supporting responsible lending, managing financial risk, and facilitating informed property investment decisions.
Property valuation in Qatar: frequently asked questions
Do banks in Qatar require a property valuation for a mortgage?
Yes. A mortgage in Qatar is secured against the property itself, so banks rely on an independent opinion of market value from a qualified valuer before they lend.
What is the loan to value (LTV) for a mortgage in Qatar?
The Qatar Central Bank sets the maximum LTV. For residential property, Qatari citizens can borrow up to 80% of the value (up to QAR 6 million) and 75% above that, with a maximum tenure of 30 years.
Can expats get a mortgage in Qatar?
Yes. Resident expatriates buying residential property can borrow up to 75% of the value for properties up to QAR 6 million and 70% above that, with a maximum tenure of 25 years. If you are new to buying here, read our guide on whether foreigners can buy property in Qatar.
How much can I borrow for a mortgage in Qatar?
It depends on the property valuation and the LTV limit for your category, as well as your income, existing financial obligations and credit history. Qatar Central Bank rules also cap monthly repayments at 75% of salary for Qataris and 50% for expatriates, according to the Qatar News Agency.
What does a valuer check during a property valuation in Qatar?
The valuer inspects the property and looks at its location and surroundings, physical condition, size and permitted use, legal standing, comparable transactions nearby and, for investment property, its income potential.
Which valuation methods do banks in Qatar use?
Residential property is usually valued with the comparison approach, using recent sales of similar properties. Commercial property often needs an income and market assessment.
How much does a property valuation in Qatar cost?
Fees depend on the type, size and complexity of the property. Contact our valuation team for a quote.
Get a property valuation in Qatar with Capstone Property
At Capstone Property, we help buyers, investors and developers understand what their property is worth and how that value will be viewed by lenders. Talk to our team before you apply for financing, and walk into the process with a clear picture.
Get your property valued by our team of RICS Registered Valuers.
Email: valuations@capstoneproperty.com · Phone: +974 3022 2086
This article is for general information only and does not constitute financial or legal advice. Lending rules and bank policies change, so always confirm current requirements with your bank.